A Meta ad refund can be refused after Meta's own chat promised it. In the account behind this piece, automated support said closing a wrong ad account would refund its $75 balance to the original payment method automatically. Three months later a new ticket calls that payment non-refundable. Your card's dispute clock did not pause for any of it. So before you open another ticket, do one check: find the date of the first card statement that shows the top-up.
Your card's 60-day dispute window decides how long you have, whatever Meta's tickets say.
- If the first statement showing the top-up is 60 days old or less, counting post time, send the issuer a written billing-error notice now.
- Older than that, the FTC route has probably closed; read your card agreement and still ask Meta in writing.
- Do not close the ad account until Meta confirms in writing where the balance goes.
- This covers US credit cards only. Debit cards and other countries follow different rules.
Why is a Meta ad refund really a card-statement deadline?
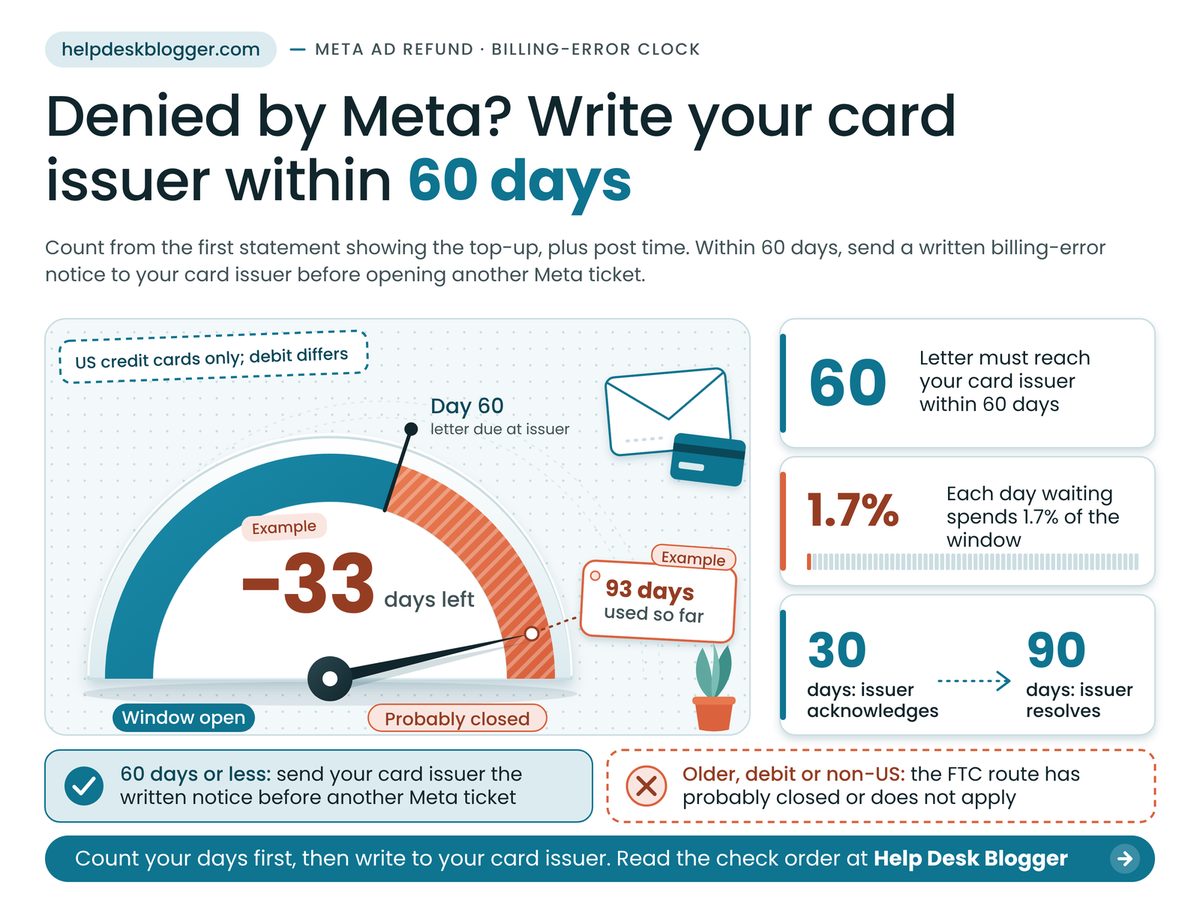
Because the one deadline we could verify belongs to your card issuer: under the FTC's guidance for US credit cards, a written dispute must reach the issuer within 60 days of the first bill showing the error.
Here is the rule's own wording, from the FTC's consumer page on disputing charges (last modified 2 April 2024, read 13 November 2026). Your letter must reach the issuer "within 60 days after the first bill with the error was sent to you." Plain reading: the clock starts at the statement, not at Meta's last reply.
Dates ignore your queue. The Secure Boot certificate that expired on 19 October 2026 and Office 2021 support, which ended on 13 October 2026, both arrived on schedule. A card dispute works the same way.
Two more details decide whether the letter counts. The FTC says to "use the address given for billing inquiries, not the address for sending your payments," so a letter to the payments address may not count. Then the issuer must acknowledge your complaint in writing within 30 days and resolve it within 90. Those two dates give the whole fight an end.
Four numbers set your room. The last card is our own arithmetic; the rest come from the sources above.
Window to Write the Issuer
60 days
From the first statement showing it
Money Frozen in the Wrong Account
$75
Still stuck three months on
Clocks in the Card Rule
3 clocks
You write; the issuer answers and resolves
Window Spent per Day of Waiting
1.7%
Our arithmetic: one day in sixty
The first clock is the only one you control, and it is a letter, not a ticket. Keep proof of the day it arrived: the rule counts arrival, not posting. The other two belong to the issuer.
Support replies do not pause your card's clock. The 60 days count from the statement, whatever the ticket says.
Worked example: take a $75 top-up whose first card-statement line is 90 days old (three months, or near enough) and a letter that needs 3 days to reach the issuer. Both are assumptions; type your own below. Days used: 90 + 3 = 93. Window: 60. Dispute days left: 60 - 93 = -33 days. Negative means the window has likely closed. In the case behind this piece, it shut about 30 days before the new ticket called the payment non-refundable.
What should you do, based on your statement's age?
The right move depends on two things you can check in minutes: how many days ago the top-up first appeared on a statement, and whether you paid with a US credit card.
| If you are | Do this | Because |
|---|---|---|
| ⏱ 0-50 days | Mail a tracked billing-error letter now | Leaves room for post time |
| ⏱ 51-60 days | Courier it today, with proof | Arrival counts, not posting |
| ⏱ Over 60 days | Read your card agreement; write Meta too | FTC window has probably closed |
| 🌍 Debit or non-US | Ask your bank for its dispute window | FTC page covers US credit cards |
| 🛠 Any case | Ask Meta in writing: cash or credit? | Credit would not repay your card |
Our arithmetic: 60 days less up to 10 days in the post gives the 50-day line. Find your row and read across. The 51-60 row is the trap. It looks open, but a letter posted on day 59 arrives late.
Near day 60, the card letter comes before any more Meta tickets: the window closes whether or not Meta has answered. Our arithmetic: 60 days is the FTC's figure; the 90-day span is the three months reported in the case behind this piece.
What can still go wrong with a card dispute?
A card dispute can still fail: the issuer may treat a wrong-account top-up as a charge you authorised, and a letter that arrives after day 60 loses the FTC route. Our view on the first: a grey area. The FTC lists things you "didn't accept or weren't delivered as agreed" as disputable. Whether a wrong-account top-up fits is the issuer's call. We would cite the wording anyway.
Support loops are the second risk. A founder wrote in an undated company blog post that Meta collections said "we haven't received the payment that you have made via Credit Card", and the case was closed as completed. An AdExchanger trade column of 14 March 2024 put it bluntly: "the only party to complain to is an automated rep." Both are single accounts, not statistics.
The same column reports refunds that came back as ad credits, so ask in writing whether yours is cash or credit. And do not close an account on a chat's promise. Closing cannot be undone, the same caution as with a Wemo that stopped working after Belkin's shutdown.
- The FTC lets you withhold a disputed amount, but a prepaid top-up is already paid.
- We could not read Meta's help pages. The "closing refunds automatically" line is one advertiser's report of a chat.
- No written acknowledgement after 30 days means you chase the issuer.
Check these about your own case before you write
- You can open the statement that first shows the top-up and read its date.
- Your card is a US credit card, not debit or UPI.
- You hold the issuer's billing-inquiry address, not its payments address.
- Meta's answer on cash or credit is in writing, not only in chat.
This week, add two numbers: the days since the first statement showing the top-up, and the days a letter needs to reach the issuer. If the total is 60 or less, send a written billing-error notice to the billing-inquiry address before you open another Meta ticket. Subtract it from 60 for your dispute days left. Over 60, or paying by debit or a card outside the US, the FTC route has probably closed or does not apply: read your card agreement and still write to Meta. Our call is wrong if your issuer rules a wrong-account top-up an authorised charge. The one check is the issuer's written answer, and the FTC's guide to disputing credit card charges is where to start.
How we checked this
We read the FTC's page on disputing charges on 13 November 2026 (last modified 2 April 2024). Meta's help pages, About refunds for ads and Types of refunds, blocked our fetcher, so we make no claim about Meta's rules. The opening case is one advertiser's account, relayed by the editor and not confirmed by Meta. The worked example assumes a 90-day-old statement and 3 days of post. No product was tested hands-on for this article.
Last verified: 13 November 2026. Edited by Ragu, reviewed after publication. Spotted something out of date? Tell us and we will correct it.